





 We support and stand by Ukraine in its fight for freedom.


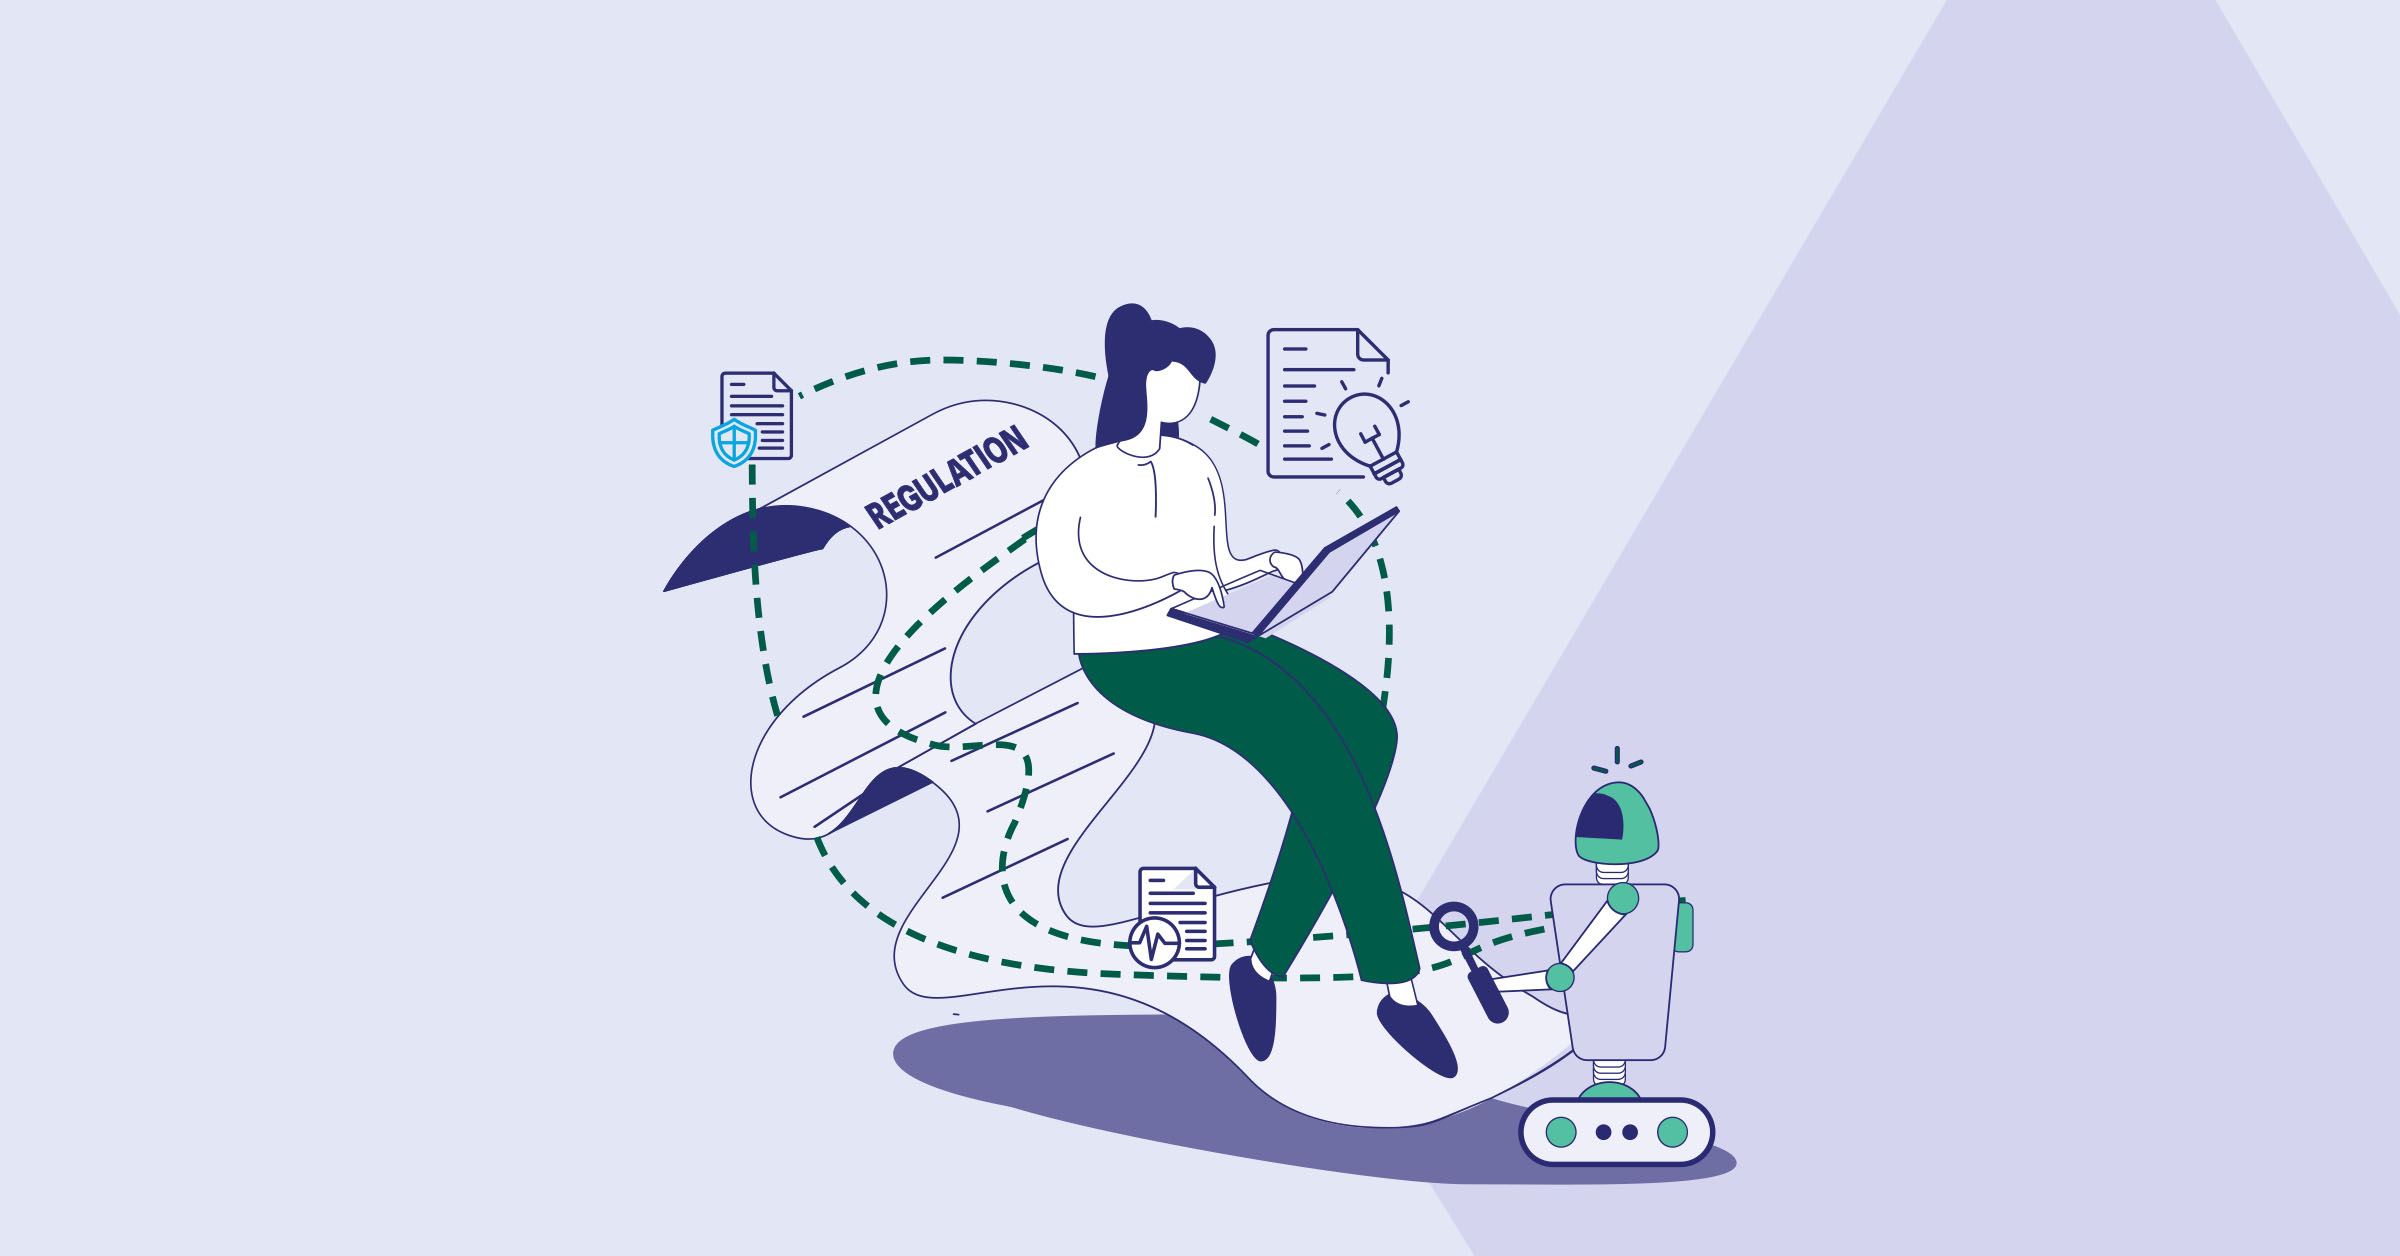
For life insurers, the agentic AI conversation often starts with regulation, because it has to.
When AI is used in life insurance, it can influence some of the most consequential decisions an insurer makes: risk assessment, pricing, underwriting, coverage, servicing, and claims.
Europe has gone as far as specifically classifying AI used for risk assessment and pricing of individuals in life and health insurance as a high-risk category under the EU AI Act.
The U.S. isn’t following the same regulatory model, but life insurers wanting to deploy AI are still under plenty of regulatory pressure there as well. Regulators are moving toward examination-ready expectations concerning where AI is used, what data supports it, how outputs are tested, whether unfair discrimination has been evaluated, what vendors are involved, and how customers can obtain review when automated technology materially affects a decision.
This becomes even more important when we move from generative AI to agentic AI that can actually take action and get work done within an insurer’s core system.
Life insurers have no shortage of jobs for AI agents
For life insurers, AI agents could help them collect outstanding underwriting evidence, reconcile application information, identify missing requirements, prepare communications, coordinate third-party data, initiate policy servicing tasks, assist claims teams, and move routine cases forward without requiring employees to manually push each one through the process.
With so much potential for efficiency, solving governance issues is a must for life insurers who want to take advantage of it.
An insurer can’t simply ask whether its agent reached the right answer — due to regulations, they’ll need to demonstrate which information the agent used, whether that information was permitted, which rules applied, why the action was taken, whether human oversight was required, and what changed in the system as a result.
Further, these questions and requirements may change depending on the different jurisdictions a life insurer operates in.
Old system architecture makes new AI regulatory requirements harder than they need to be
Many carriers will try to solve agentic AI at the experience layer, which involves buying an AI solution, connecting it to their core, adding a few APIs, and start building agents.
This approach can look great in a demo, but it becomes far less charming once production actually begins.
Because modern legacy systems were built around architectures that make data movement, integration, and rapid configuration harder, things can become overly complex rather quickly.
Imagine an underwriting agent trying to determine the appropriate next action when a customer’s information exists across multiple policy, CRM, document, and third-party systems… Which record “wins” as the record of truth?
Or imagine that a regulatory requirement changes in one state. Would the insurer be able to update the applicable rule and its effective date directly, or does IT need to alter custom code, test integrations, and coordinate another release?
While agentic AI promises a dramatic reduction in the cost and time required to perform work, the ability to do so weakens significantly if every regulatory change still moves at the speed of legacy implementation.
EIS, on the other hand, offers a cloud-native infrastructure, an event-driven and customer-centric architecture, microservices, open APIs, near-real-time data fluidity, and configuration designed to reduce hard-coded change.
Solution: Put regulatory compliance into the execution layer with EIS
EIS OneSuite™ powered by CoreGentic™, brings agentic AI into the insurance core itself.
CoreGentic can orchestrate AI-driven work using the same insurance context that supports product definitions, underwriting rules, eligibility, customer and policy data, workflows, permissions, and lifecycle processes.
With PolicyCoreⓇ capabilities within EIS, insurers can configure products, underwriting rules, eligibility criteria, versioning, and lifecycle processes across quoting, risk assessment, issuance, changes, and renewals. Business rules can be configured to reflect jurisdiction-specific requirements, letting the operating system enforce those rules as transactions occur.
EIS also provides workflow management, security controls, event-driven processing, and Business Activity Monitoring (BAM). BAM maintains detailed activity histories associated with entities such as policies, claims, billing, and quotes, creating the operational traceability insurers need as AI takes more action.
Further, we were the first insurance core system vendor to obtain ISO/IEC 42001 certification for AI management systems, proving our AI leadership in the market.
CoreGentic gives insurers the opportunity to extend that governed environment into agentic orchestration: AI can take on more work without separating the agent from the rules, data, controls, and records that make the work defensible. This allows life insurers to be ambitious with agentic AI, but also retain the governed autonomy needed for both efficiency and regulatory compliance.
Optimize Your Life Insurance Agentic AI Strategy
Embracing agentic AI doesn’t require sacrificing compliance or operational integrity when supported by a modern, governable insurance core like EIS OneSuite powered by CoreGentic.
Book a call with us today to see what’s possible and learn how you can safely accelerate your AI initiatives.